
Matching Private-Equity Exposure While Capital Waits
- Private-equity exposure builds slowly. On a steady primary commitment pace, an average of 71% of the intended allocation sits outside the asset class over the first five years.
- For asset owners, the choice of interim holding (cash, broad listed equity or an exposure-matched tracker) is worth 4.1 percentage points a year on the allocation, of which 1.3 points comes from exposure composition alone.
- An exposure-matched tracker beat broad equity in 39 of 39 10-year cohorts, by an average of 187 basis points (bps), and 539 bps against cash. The interim holding deserves the same scrutiny as the target.
Mentioned in this blog post:
Capital committed to private equity takes years to reach the intended exposure. We examine the options for holding the undeployed balance during that period and estimate what each choice is worth.
In private equity, capital is typically not invested on the day an allocation is approved. Until the target exposure is reached, much of the intended allocation is invested in something else. The interim holding is an allocation decision too, but it is rarely subjected to the governance applied to the target it temporarily replaces.
For example, an investor with a USD 20 billion portfolio and a 10% target (USD 2 billion) in private equity commits USD 440 million a year and reaches the target in year 10. In year one, 96% of the intended allocation is still outside private equity. Over the first five years, the average is 71%.1
Illustrative. Steady annual commitments of USD 440 million against a 10% target, with a stylized vintage NAV profile.
Capital awaiting commitment is under the investor's control. The investor chooses when to move the money, but selecting managers and staging commitments across vintages takes years. We refer to this as the ramp.
Committed but uncalled capital works differently: The general partner decides when to draw it, so the investor must be able to liquidate on demand, whatever market conditions prevail. We refer to this as the commitment gap. The ramp is a horizon to manage; the commitment gap is a liability to meet.
Both kinds of undeployed capital must sit somewhere while they wait. In practice, that is almost always cash or broad listed equity, and each falls short in a different way.
Cash is unambiguously available when a call arrives, but from 2007 to 2026 the MSCI Cash Index returned 1.66% annualized against 12.33% for the MSCI Global Developed Private Equity Closed-End Fund Index (PE Index).
Broad public equity, on the other hand, closes most of that return gap, but private-equity portfolios are concentrated in ways a broad public-equity index is not. An investor who parks the balance in a broad public-equity index can reach full deployment with a return that bears little relation to what private equity earned over that period.
In addition to being liquid, the interim holding must resemble the private-equity portfolio being built rather than the broad equity market.
The MSCI World Private Equity Return Tracker Index (World PERT Index) is a public-equity index built to approximate private-equity exposures. Its premise is that part of private-equity return comes from measurable characteristics (i.e., sector, country, styles) that listed equities can reproduce. The rest comes from the work general partners do in sourcing, selecting and operating companies, which listed equities cannot replicate.
Construction follows that split: The index reweights listed equities to match the sector, country and style-factor exposures of the private-equity universe, across strategies and regions.
From Q1 2007 to Q2 2026, the PE Index returned 12.33% annualized, the tracker index 11.42% and the MSCI World IMITM 8.23%. The tracker captured 319 of the 410 basis points separating the PE Index from World IMI, leaving 92 basis points attributable to manager skill and other unreplicable factors.
We apply those returns to the pacing schedule, splitting the allocation each year between deployed private equity and the interim holding. The allocation as a whole then returns 11.96% a year with the World PERT Index, 10.65% with broad listed equity and 7.91% with cash.
Hypothetical. Annualized index returns for Q1 2007 to Q2 2026 applied to the pacing schedule. The dashed line represents immediate full deployment, which is not attainable.
We repeated the exercise, running a complete 10-year program from every available start quarter. This yields 39 overlapping cohorts beginning between Q1 2007 and Q3 2016. These windows overlap substantially and are not independent observations, so no statistical inference can be drawn from them.
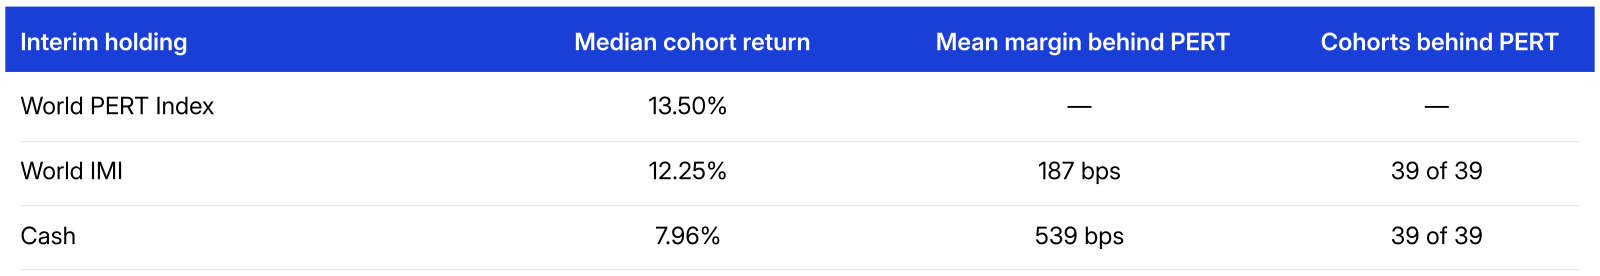
Hypothetical. Each observation is a complete 10-year program using realized quarterly returns. Thirty-nine overlapping cohorts, from Q1 2007 to Q3 2016.
The returns are what can be measured, and the differences are large enough to report, but they are not the argument. The capital stands in for private equity while it waits, so it must look like private equity. That exposure match is the point. The return gaps reflect this particular window, and another window would produce other numbers.
The period before a private-equity program reaches its target is not a procedural interval. It is a material allocation, frequently measured in hundreds of millions or billions, and the instrument chosen to hold it affects the return of the program as a whole.
The tracker index suits the ramp period, where the investor controls the exit and the question is exposure composition. The commitment gap is harder. Capital calls may arrive when markets are falling, forcing a sale of the interim holding at the worst moment. Holding the next year or two of expected calls in cash, with the rest in the tracker, addresses most of that. An investor who prefers to stay invested can instead buy downside protection on the equity exposure, through puts or a collar. This limits the loss on a forced sale, at the cost of part of the return advantage. Whichever route is taken, the interim allocation must be the outcome of a deliberate decision rather than a residual.
Subscribe todayto have insights delivered to your inbox.
MSCI World Private Equity Return Tracker Index
Target private equity-like returns with the liquidity of public markets with an innovative index designed to reflect the systematic drivers of private equity performance.
Rethinking Access to Private Equity
We present an index that uses listed securities to reflect the drivers of private-equity returns, aiming to help bridge the gap between private and public markets.
Tracking Private Equity
MSCI’s new deal-level fundamentals and private markets returns data can be used to separate what can be replicated in the public markets from the unique value added by private equity.
1 Pacing assumptions used in the first two charts. A USD 20 billion portfolio with a 10% target allocation, or USD 2 billion, held constant so the target does not move. Commitments of USD 440 million are made at the start of each year and sustained. Each vintage's net asset value, as a share of its commitment, follows 20%, 42%, 60%, 70%, 72%, 65%, 52%, 38%, 25%, 14% and 6% across years one to 11 and zero thereafter, peaking at 72% in year five. Total exposure in any year is the sum across live vintages, which gives deployed shares of the target of 4%, 14%, 27%, 42%, 58%, 72%, 84%, 92%, 98% and 100% in years one to 10; the model's marginal overshoot in year 10 is held at the target. For the cohort analysis in the table, these annual shares are interpolated linearly to quarterly steps. The profile is stylized rather than estimated from fund cash-flow data, and the results scale with the size of the allocation but not with its composition.
The specific figures follow from the pacing assumption and are illustrative rather than representative. An investor deploying through secondaries, co-investments or an overcommitment policy would reach target sooner, and one with a narrower manager roster might take longer. What generalizes is the shape: exposure builds over years, and the undeployed share is largest early, when it is least likely to be examined.
The content of this page is for informational purposes only and is intended for institutional professionals with the analytical resources and tools necessary to interpret any performance information. Nothing herein is intended to recommend any product, tool or service. For all references to laws, rules or regulations, please note that the information is provided “as is” and does not constitute legal advice or any binding interpretation. Any approach to comply with regulatory or policy initiatives should be discussed with your own legal counsel and/or the relevant competent authority, as needed.