
Halfway to 2030, COP17 Leaves Finance Unresolved
- COP17 advanced biodiversity action with around USD 2 billion in new pledges, but left key financing questions unresolved. Investors must navigate policy uncertainty while acting on risks they can already assess.
- Nature data is increasingly informing investor engagement: 73% of surveyed investors used nature assessments for stewardship, against 23% for capital allocation. Supply-chain visibility and data quality remain challenges.
- The next frontier is financial materiality: attributing changes in nature to company-level financial losses, understanding who bears them and developing scenarios that connect nature science with financial decisions.
Mentioned in this blog post:
The UN Biodiversity Conference (COP17) in Yerevan, Armenia, marked the halfway point toward the 2030 targets of the Kunming-Montreal Global Biodiversity Framework. The first global review found 22 of 23 targets off track.1 Countries adopted the Yerevan Pathway, but contentious financing questions were deferred to COP18 in 2028.
For investors, the implications of policy decisions such as reforming environmentally harmful subsidies remain uncertain. But financial institutions and companies are already working on more immediate questions: How can nature-related data inform decisions today, and what still needs to improve?
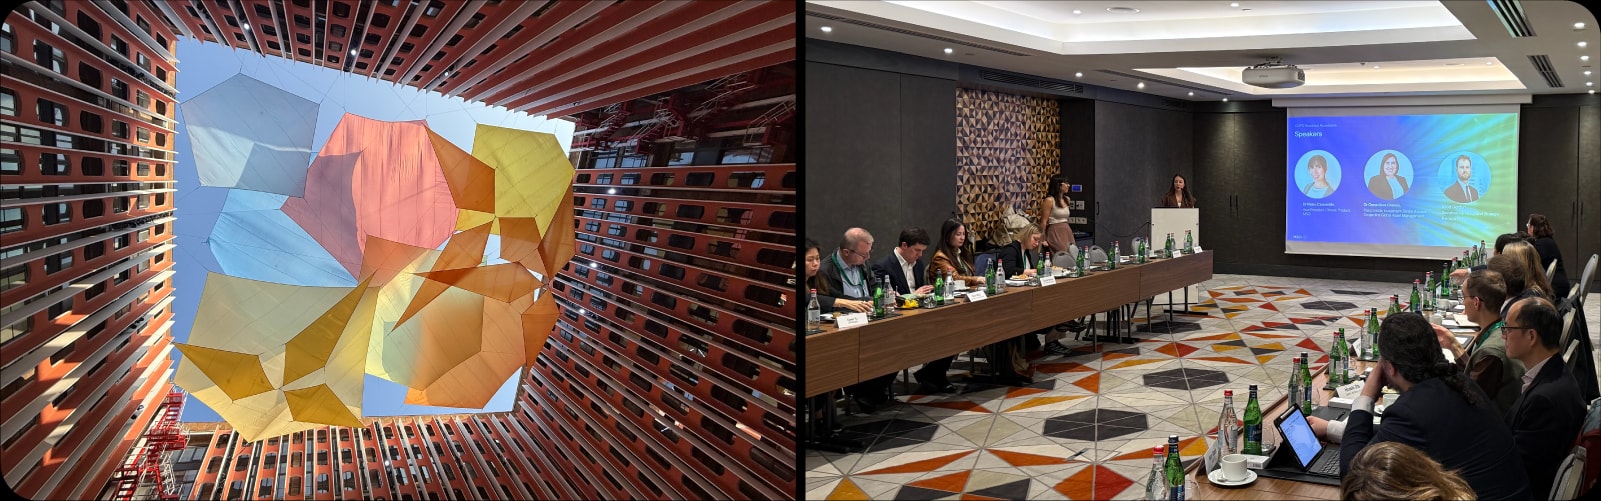
Left: A butterfly-inspired art installation at COP17’s Blue Zone in Yerevan, Armenia, reflects the conference’s official emblem, a species endemic to Armenia — a reminder that biodiversity is both a local and global concern.
Right: Speakers sharing climate and sustainability insights at the COP17 Breakfast Roundtable, hosted by MSCI.
For years, lack of data has been a recurring obstacle to assessing nature-related risks. At COP17, the discussion had moved on: Data availability has improved, and the question is increasingly which data suits which decision.
An investor screening thousands of companies needs different information from a manufacturer assessing individual supplier locations. Public and modeled datasets can provide a starting point; more detailed assessments require appropriate coverage, resolution and reliability.
Gaps remain in supply-chain transparency, information on company risk management and evidence linking changes in nature to financial losses. Supply chains illustrate the challenge: Companies generally struggle to gain full visibility of their supply chains. The bigger problem is that the suppliers a company knows are often not the ones whose disruption would hurt most. Supply chains are where the broader gaps show up most clearly: how companies manage nature-related risk, and the evidence linking nature loss to financial losses.
Modeled supply-chain relationships can help as a stand-in for these gaps, with more granular information used to investigate and validate findings.
Nature-related information does not necessarily drive portfolio reallocation, but it is increasingly informing engagement and risk management. The Taskforce on Nature-related Financial Disclosures (TNFD) 2026 Status Report supports this distinction: Among 40 surveyed investors that had undertaken nature-related Locate, Evaluate, Assess, Prepare (LEAP) assessments, the TNFD approach for identifying nature-related dependencies, impacts, risks and opportunities, 73% used them for stewardship, compared with 23% for capital allocation.
At our breakfast roundtable, we discussed a joint MSCI–Desjardins case study on using nature data to compare companies and inform engagement. The discussion highlighted a limitation: Public data did not always reflect what investors knew from past engagements. Companies with strong practices could be difficult to distinguish from peers.
Sometimes this reflects intentional information management: We heard of companies withholding disclosures over political concerns or because their operating locations are commercially sensitive. Investors can use third-party data as a conversation starter, giving companies something specific to confirm, challenge or explain.
Knowing where a company is exposed to nature-related risks is not the same as knowing what those risks could cost. The TNFD's 2026 Status Report survey found that 69% of 206 respondents reported difficulties linking nature-related dependencies and impacts to business risks, including financial effects.
A recurring theme in our discussions was the importance of attribution: establishing how a change in nature translates into financial losses, and who bears them. Empirical evidence from past events is accumulating but remains scattered and difficult to compare. Collecting and standardizing this evidence is essential both to demonstrate financial materiality and to build models of future losses. We have applied this approach in our research on water scarcity, drawing on reported drought losses to estimate financial impacts across companies' operations and supply chains.
Materiality is, however, not only about the how but also the to whom. A risk that is financially material to a company may have very different consequences for its lenders, shareholders or insurers. As one attendee observed, insurance can provide an early warning signal because insurers must already price some of these risks.
Financial institutions also need to assess how nature-related risks could change under different future scenarios.
Unlike climate, nature lacks well-established, internationally coordinated scenario-modeling programs. Discussions in Yerevan highlighted the need for stronger scientific foundations, comparable methodologies and, crucially, scenarios that translate changes in ecosystems and nature into financially relevant outcomes.
The negotiations in Yerevan showed how much remains unresolved on the road to 2030. Important policy and financing questions remain open, while gaps in data, attribution and scenario modeling still need to be addressed. Closing these gaps will require continued work across the scientific and financial communities, including ourselves at MSCI.
But nature-related risks won't wait for the policy process to catch up, or for the data and models to be perfected. Nor are financial institutions standing still: Many are already using the information available to identify exposures, challenge companies and inform decisions. What is clear is that acting now beats waiting for perfect data.
For investors, a practical starting point is to run their holdings through nature data this quarter, compare the results with what they already know from engagement and use the gaps to set the next round of company questions.
Subscribe todayto have insights delivered to your inbox.
From Awareness to Action: Assessing Nature-Related Physical Risks
Nature-related risk depends on where companies operate. MSCI’s Nature Risk Matrix assesses 163 sub-industries across seven risk types. See where risks are concentrated.
Water Scarcity: Who Picks Up the Bill?
Water scarcity could cost companies an estimated USD 485 billion annually, with impacts extending far beyond drought-hit regions. Who picks up the bill, and where are the hidden exposures?
Nature and Biodiversity Solutions
Identify and measure nature- and biodiversity-related risks and impacts.
1 Aruna Chandrasekhar, Daisy Dunne, Orla Dwyer, Molly Lempriere and Giuliana Viglione, "COP17: Key outcomes agreed at the UN biodiversity conference in Yerevan," Carbon Brief, 31 Oct. 2026 (updated 4 Nov. 2026).
The content of this page is for informational purposes only and is intended for institutional professionals with the analytical resources and tools necessary to interpret any performance information. Nothing herein is intended to recommend any product, tool or service. For all references to laws, rules or regulations, please note that the information is provided “as is” and does not constitute legal advice or any binding interpretation. Any approach to comply with regulatory or policy initiatives should be discussed with your own legal counsel and/or the relevant competent authority, as needed.